The Household Fast: What Voluntary Limits Teach Us About Money

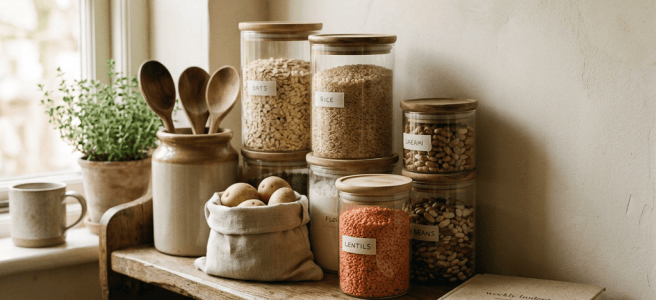
Wooden shelf with labeled jars of oats, rice, lentils, and beans

I have a bad habit of treating the grocery cart like a tiny casino. I walk in for milk and come out with crackers, a candle, and a snack whose flavor appears to be “seasonal confidence.” The budget did not approve this pilgrimage.

That is why fasting has started to look less like a grim test of willpower and more like a useful household practice: a voluntary limit that helps me notice what usually runs on autopilot.

In the Catholic tradition, fasting is not simply “eat less and feel impressive.” The United States Conference of Catholic Bishops describes fasting as part of Lent’s preparation, with concrete norms and room for common sense. The practice is meant to turn attention, not to reward spiritual theatrics.

Jesus makes that interior point plainly in Matthew 6:16–18. Do not perform your hunger for an audience. Wash your face. Keep the thing honest. A fast that becomes a personal brand has wandered off and started charging admission.

Now translate that posture into a household budget. Pick one small category—takeout, online shopping, coffee runs, impulse purchases—and set a temporary boundary. Not forever. Not as penance for being a flawed mammal. Maybe seven days. Maybe the stretch between two paychecks.

The Consumer Financial Protection Bureau’s spending-rule worksheet suggests choosing a weekly or monthly limit for “wants,” writing it down, and keeping the rule visible. That is a remarkably humble technology: paper, a number, and the mild discomfort of having promised yourself something in ink.

There is a reason the little rule can help. Research in the Journal of Consumer Research describes precommitment as a way people place boundaries around future choices when they know temptation will arrive later. In other words, you are not declaring yourself stronger than temptation. You are moving the furniture before temptation walks in.

Try this: before the week begins, write three lines—what I am abstaining from, what counts as an exception, and where the unspent money will go. Savings is fine. A charitable gift is fine. A family breakfast is also fine. The point is not to make deprivation the hero. The point is to make attention available for something better.

Then do the evening examen, but with receipts. What happened? I reached for convenience more often than I expected. What did it mean? My spending was carrying moods I had not named. What will I carry forward? One modest rule, renewed regularly, can teach a household where its “yes” is meant to go.

Fasting is not a magic trick, and a budget is not a moral scoreboard. But both can become small acts of freedom: a pause long enough to ask, kindly, “Do we actually want this?”
The Examen and the Expense Report: A Better Way to End the Day

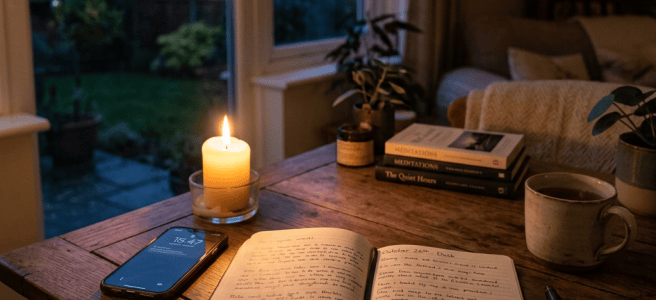
Open journal with handwritten notes, lit candle, smartphone, books, and cup of tea on wooden table at dusk

I have two end-of-day rituals, at least in theory. One is spiritual: the examen, that quiet Ignatian habit of looking back over the day with God. The other is financial: opening the bank app and asking where the money went. One sounds holy. The other sounds like a small punishment invented by a spreadsheet.

But they have more in common than I expected. Both are practices of attention. Both ask us to stop guessing and look honestly at the day we actually lived—not the day we intended to live, or the budget we intended to keep.

The daily review is not a courtroom

The Jesuits describe the Ignatian Examen as a prayerful review: become aware of God’s presence, give thanks, notice what happened, and look toward tomorrow. The point is not to produce a perfect scorecard. It is to become more awake to where we were alive, distracted, generous, anxious, or quietly carried.

A financial review works best with the same posture. Start with the facts: the grocery run, the subscription renewal, the restaurant charge that seemed harmless until it joined its twelve little cousins. Then ask a gentler question than “What is wrong with me?” Ask: “What was I seeking?” Convenience? Rest? Belonging? A reward after a long day? The numbers are not a moral verdict. They are clues.

Attention turns into agency

The Consumer Financial Protection Bureau recommends tracking spending for at least two weeks, or even a month, so patterns become visible. That is a wonderfully unglamorous form of freedom. You cannot choose what to change until you can see what is happening.

This is where the spiritual and financial reviews meet. In the examen, I might notice that a certain conversation left me impatient. In the ledger, I might notice that the same kind of day ends with delivery food and late-night shopping. Neither observation is the whole story. Together, they might reveal a need for a better pause before I reach for the easiest relief.

And “better” does not have to mean dramatic. Investor.gov suggests keeping track of income and expenses and including savings in the picture. For tonight, that could mean writing down three purchases, one gratitude, and one small adjustment for tomorrow. No overhaul. No financial monasticism. Just a little light.

What happened, what it meant, what to carry forward

What happened? I spent the day making choices, some deliberate and some automatic. What did it mean? My attention—and my money—moved toward whatever felt urgent, comforting, or important in the moment. What can I carry forward? A five-minute review, done without self-contempt, can turn a blur into a pattern. A pattern can become a choice.

Tonight, before closing the banking app, try one question from each practice: “Where did I receive a gift today?” and “What did my spending say mattered?” The answers may not match perfectly. That is not failure. That is information—and information is a decent place to begin again.