Praying With Your Kids About Money Without Making It Weird

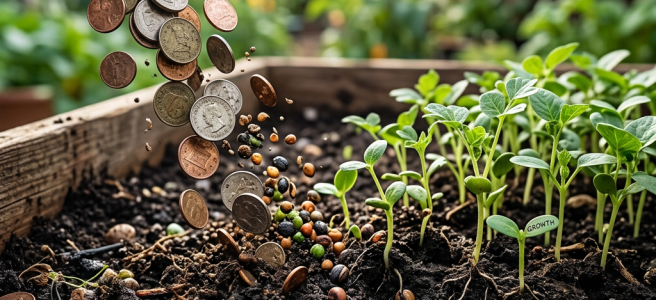
Coins and seeds pour into a garden bed beside seedlings labeled “GROWTH”

I used to think praying with kids about money would be simple. “Thank you for what we have. Help us share. Amen.” Neat little package. Then a child asks, “If God loves us, can we get the giant box of cereal?” and suddenly the family theology department is taking questions.

Money is awkward because it carries so many adult feelings: worry, pride, comparison, secrecy, gratitude. Children notice those feelings before they understand a budget. The goal is not to give a five-year-old a quarterly earnings call. It is to make money ordinary enough that it can be discussed without becoming either a family secret or a family sermon.

The Consumer Financial Protection Bureau says school-age children are learning to save, plan ahead, wait for what they want, and connect choices with their own goals and values. It also points out that children watch us: the bargain we celebrate, the treat we splurge on, the future event we plan. The CFPB’s money-milestone guide suggests thinking out loud about those choices. That is already a kind of lesson—and, if we are paying attention, a kind of examination of conscience.

Research points in the same direction. In a qualitative study of 90 emerging adults, along with 17 parents and 8 grandparents, families described three helpful patterns: sharing financial experiences, involving children in decisions, and keeping conversations age-appropriate. The paper, “Can We Talk About Money?”, is not a command to turn every grocery trip into a seminar. It is a reminder that children learn through conversation and participation, not only through warnings delivered from the driver’s seat.

Prayer can give that conversation a gentler frame. The Catechism describes the family as a place where, from childhood, people learn moral values and “make good use of freedom,” and where members learn responsibility for one another. Read paragraphs 2207–2208 and you hear less about money as a scorecard than money as part of learning how to live with other people.

Try a three-part prayer once a week: “Thank you for what we have. Help us choose wisely. Show us someone we can help.” Then attach it to one concrete thing. We are saving for a trip. We are waiting before buying this toy. We are setting aside a gift for a neighbor. The point is not to make the child perform generosity on cue. It is to let them see that money can be received with gratitude, handled with care, and shared with love—the basic shape of Christian stewardship.

A few guardrails help. Do not make God sound like an ATM. Do not shame a child for wanting something. Do not pretend the family has no limits. Say, “That is a real want, and it is not what we are choosing today.” If the family is under financial strain, offer an age-appropriate truth without handing a child the whole burden: “We are being careful right now, and the grown-ups are making a plan.”

What happened? A money question became a prayer instead of a panic. What did it mean? The child learned that faith touches the checkout line, but does not erase reality. What can we carry forward? One honest sentence, one small choice, and one person to remember in prayer. That is not weird. That is formation, with a receipt attached.
The Examen and the Expense Report: A Better Way to End the Day

Open journal with handwritten notes, lit candle, smartphone, books, and cup of tea on wooden table at dusk

I have two end-of-day rituals, at least in theory. One is spiritual: the examen, that quiet Ignatian habit of looking back over the day with God. The other is financial: opening the bank app and asking where the money went. One sounds holy. The other sounds like a small punishment invented by a spreadsheet.

But they have more in common than I expected. Both are practices of attention. Both ask us to stop guessing and look honestly at the day we actually lived—not the day we intended to live, or the budget we intended to keep.

The daily review is not a courtroom

The Jesuits describe the Ignatian Examen as a prayerful review: become aware of God’s presence, give thanks, notice what happened, and look toward tomorrow. The point is not to produce a perfect scorecard. It is to become more awake to where we were alive, distracted, generous, anxious, or quietly carried.

A financial review works best with the same posture. Start with the facts: the grocery run, the subscription renewal, the restaurant charge that seemed harmless until it joined its twelve little cousins. Then ask a gentler question than “What is wrong with me?” Ask: “What was I seeking?” Convenience? Rest? Belonging? A reward after a long day? The numbers are not a moral verdict. They are clues.

Attention turns into agency

The Consumer Financial Protection Bureau recommends tracking spending for at least two weeks, or even a month, so patterns become visible. That is a wonderfully unglamorous form of freedom. You cannot choose what to change until you can see what is happening.

This is where the spiritual and financial reviews meet. In the examen, I might notice that a certain conversation left me impatient. In the ledger, I might notice that the same kind of day ends with delivery food and late-night shopping. Neither observation is the whole story. Together, they might reveal a need for a better pause before I reach for the easiest relief.

And “better” does not have to mean dramatic. Investor.gov suggests keeping track of income and expenses and including savings in the picture. For tonight, that could mean writing down three purchases, one gratitude, and one small adjustment for tomorrow. No overhaul. No financial monasticism. Just a little light.

What happened, what it meant, what to carry forward

What happened? I spent the day making choices, some deliberate and some automatic. What did it mean? My attention—and my money—moved toward whatever felt urgent, comforting, or important in the moment. What can I carry forward? A five-minute review, done without self-contempt, can turn a blur into a pattern. A pattern can become a choice.

Tonight, before closing the banking app, try one question from each practice: “Where did I receive a gift today?” and “What did my spending say mattered?” The answers may not match perfectly. That is not failure. That is information—and information is a decent place to begin again.