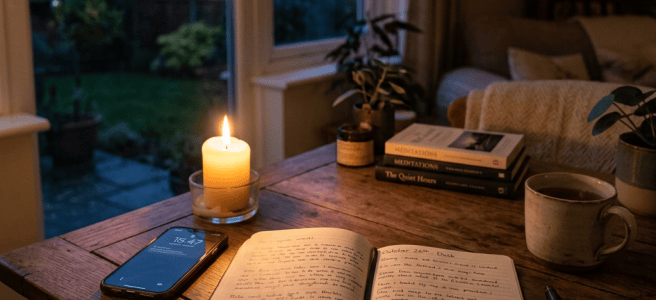
I have two end-of-day rituals, at least in theory. One is spiritual: the examen, that quiet Ignatian habit of looking back over the day with God. The other is financial: opening the bank app and asking where the money went. One sounds holy. The other sounds like a small punishment invented by a spreadsheet.
But they have more in common than I expected. Both are practices of attention. Both ask us to stop guessing and look honestly at the day we actually lived—not the day we intended to live, or the budget we intended to keep.
The daily review is not a courtroom
The Jesuits describe the Ignatian Examen as a prayerful review: become aware of God’s presence, give thanks, notice what happened, and look toward tomorrow. The point is not to produce a perfect scorecard. It is to become more awake to where we were alive, distracted, generous, anxious, or quietly carried.
A financial review works best with the same posture. Start with the facts: the grocery run, the subscription renewal, the restaurant charge that seemed harmless until it joined its twelve little cousins. Then ask a gentler question than “What is wrong with me?” Ask: “What was I seeking?” Convenience? Rest? Belonging? A reward after a long day? The numbers are not a moral verdict. They are clues.
Attention turns into agency
The Consumer Financial Protection Bureau recommends tracking spending for at least two weeks, or even a month, so patterns become visible. That is a wonderfully unglamorous form of freedom. You cannot choose what to change until you can see what is happening.
This is where the spiritual and financial reviews meet. In the examen, I might notice that a certain conversation left me impatient. In the ledger, I might notice that the same kind of day ends with delivery food and late-night shopping. Neither observation is the whole story. Together, they might reveal a need for a better pause before I reach for the easiest relief.
And “better” does not have to mean dramatic. Investor.gov suggests keeping track of income and expenses and including savings in the picture. For tonight, that could mean writing down three purchases, one gratitude, and one small adjustment for tomorrow. No overhaul. No financial monasticism. Just a little light.
What happened, what it meant, what to carry forward
What happened? I spent the day making choices, some deliberate and some automatic. What did it mean? My attention—and my money—moved toward whatever felt urgent, comforting, or important in the moment. What can I carry forward? A five-minute review, done without self-contempt, can turn a blur into a pattern. A pattern can become a choice.
Tonight, before closing the banking app, try one question from each practice: “Where did I receive a gift today?” and “What did my spending say mattered?” The answers may not match perfectly. That is not failure. That is information—and information is a decent place to begin again.

