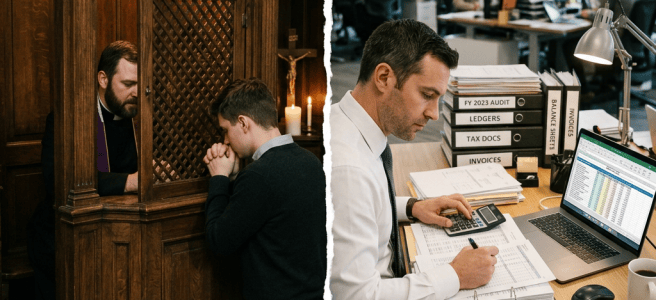
I have a confession to make: when I hear “financial audit,” my soul leaves the room and looks for snacks. An audit sounds like spreadsheets, fluorescent light, and somebody asking why a receipt from March is labeled “miscellaneous.” Yet confession and an audit share a surprisingly useful first move: they ask us to stop editing the story.
In the Catholic understanding, confession is not a performance of shame. The Catechism calls it an examination of conscience, followed by the honest disclosure of what we have done, so that responsibility and reconciliation become possible. The point is not to discover that a person is secretly terrible. It is to bring the truth into the light, where healing can begin. You can read the relevant sections in the Catechism’s account of the penitent’s acts.
An audit begins with a different kind of account, but the discipline is familiar. Management prepares the financial statements; an independent auditor examines them, tests evidence, and issues an opinion about whether they are fairly presented. The SEC’s plain-language guide to auditors is refreshingly clear about the arrangement: the people inside the company tell the story, while an outside professional checks whether the story can bear weight.
That distinction matters. A priest is not a CPA with better lighting, and God is not an investor comparing quarterly reports. Confession is sacramental and relational; an audit is professional assurance for people who need reliable financial information. Still, both practices resist the fantasy that what remains unspoken somehow does not count.
Here is where the comparison gets practical. In an audit, “material” does not simply mean “large.” A small error can matter if it changes the reader’s understanding. Our inner bookkeeping works the same way. The sharp comment we call “just stress.” The purchase we call “a one-time thing” for the seventh time. The resentment we file under “I’m fine.” Each item may look small in isolation. Together, they can reveal the habits shaping the whole household.
And neither process ends with noticing. The AICPA explains that an audit provides high, but not absolute, assurance; it produces a report that helps others make decisions. Confession, too, is aimed at a future—not merely a perfectly itemized past. The AICPA’s explanation of audits emphasizes evidence and judgment, not magical certainty. The Catechism pairs confession with satisfaction: repair what can be repaired, accept a penance, and practice a different way forward.
What happened? We hid, minimized, or misclassified something. What did it mean? The hidden line item was forming us, quietly and faithfully. What can we carry forward? Try a ten-minute weekly review: name one financial choice, one relationship, and one habit without defending yourself. Then choose one small repair. No dramatic vows. Just an honest ledger and the next faithful entry.
“What confession has in common with a financial audit.”

