The Shortcut Tax: Why Get-Rich-Quick Schemes Exploit Formation Gaps

Golden streams winding through stones toward an illuminated maze opening

I have a confession: “get rich quick” still knows exactly where to find me. Give me a tired Tuesday, a headline about someone making six figures from a laptop, and suddenly my sensible financial plan looks like it was written by a committee of very cautious squirrels.

That is the first formation gap. Not stupidity. Not greed in some cartoonish sense. Just a human being who is tired, hopeful, and ready for a shortcut.

The pitch usually arrives dressed as freedom. Quit your job. Make passive income. Turn $500 into $5,000. The Federal Trade Commission describes investment scams in almost those terms: big returns, little risk, a “proven system,” and pressure to act before you have time to think. Its consumer guidance explains the pattern.

Notice what the scheme is really selling. It is not only an investment. It is a new identity: the person who has finally figured it out. That is why screenshots of luxury cars and exploding account balances matter. They are props in a little theater of future-you.

The Securities and Exchange Commission’s investor guidance names the warning signs plainly: guarantees, “risk-free” opportunities, urgency, unlicensed sellers, and testimonials that do too much of the persuading. Its red-flag checklist is worth keeping nearby.

But the deeper problem is formation. We are shaped by what we practice, especially when nobody is grading us. If I practice clicking first and researching later, I am forming myself into a person who mistakes urgency for opportunity. If I practice asking one calm question—“How, exactly, does this make money?”—I am building a small but useful muscle.

That question is not cynicism. It is stewardship.

FINRA’s red-flag guide recommends looking closely at guarantees, unsolicited offers, secrecy, unregistered products, complex strategies, and pushy salespeople. It also says a legitimate professional should be able to explain what the investment is, how it makes money, and what the risks are. The full checklist is a useful pause button.

Here is a tiny household examen for the next irresistible pitch:

What happened? Someone offered me an unusually easy path to unusual wealth, often with a clock attached.

What did it mean? My attention was being recruited before my judgment had a chance to show up.

What can I carry forward? A pause, a second opinion, and a written explanation of the downside. If the offer cannot survive those three things, it does not deserve my money.

The goal is not to become the uncle who distrusts every new idea. Some good opportunities are unfamiliar. The goal is to become less easily hurried. Wealth is not only what we accumulate; it is also the quality of attention we bring to a decision.

And if a stranger promises that quality of attention is unnecessary, well, that may be the most expensive dad joke of all.
A Balance Sheet Is a Company’s Habit Journal

Wooden desk with paperwork, calculator, keys, coffee, and pen

I used to read a balance sheet the way I read the instructions for assembling furniture: with confidence at first, then a growing suspicion that the mysterious extra screws meant something. But a balance sheet is less mysterious than it looks. It is a snapshot of a company’s habits.

Not its whole personality. A snapshot can’t tell you everything about a person, and a balance sheet can’t tell you everything about a business. But it can show what the company has chosen to hold, what it has promised to repay, and what remains for its owners. That is already quite a lot.

Start with the simple equation

The Securities and Exchange Commission explains the basic structure plainly: assets equal liabilities plus shareholders’ equity. Assets are what a company owns or controls. Liabilities are what it owes. Equity is what would be left for the owners if the assets were sold and the obligations paid.

Think of a household. Cash in the checking account, a car, and a house are assets. A credit-card balance and a mortgage are liabilities. The difference is your rough claim on the household’s value. The analogy is imperfect — companies have inventory, patents, leases, and plenty of accounting footnotes — but it gives the numbers somewhere to sit.

Habits hide in the categories

Now look at the mix. The SEC’s balance-sheet guide distinguishes current assets, such as cash, receivables, and inventory that may turn into cash within twelve months, from long-term assets like property, equipment, patents, and goodwill. Liabilities get a similar time test: what is due soon, and what can wait?

That timing is a clue to temperament. A company with plenty of cash and manageable near-term bills may have breathing room. A company carrying heavy short-term obligations may be living payday to payday, even if its total assets look impressive. Neither picture is a verdict. It is a question: does the company’s financial posture fit the kind of business it is trying to run?

Then compare the same balance sheet across several periods. Is inventory growing faster than sales? Are receivables swelling because customers are taking longer to pay? Is debt rising to fund useful expansion, or simply to keep an old story alive? One number is a photograph. A sequence is a habit.

Read the notes, not just the headline

A company’s filing is more than the tidy table. Investor.gov notes that Form 10-K and Form 10-Q filings include financial statements, management’s discussion, risks, and notes that explain how the numbers were assembled. The notes are where “debt” can acquire a maturity date, “goodwill” can acquire a backstory, and a seemingly cheerful metric can meet its less cheerful cousin.

What happened? A balance sheet took a company’s sprawling life and froze one moment. What did it mean? The moment revealed priorities, pressures, and room to maneuver. What can we carry forward? Before buying a stock, read the statement as a pattern, then read the notes as the conversation around that pattern.

The Prompt Bank put it this way: “Reading a company’s balance sheet like reading a person’s habits.” I like that. It asks for attention without pretending to offer omniscience. And if the numbers still feel like furniture instructions, start with the equation. The extra screws can wait.

Automate the Good: Why Tithing and Saving Belong on the Same Calendar

Illustration of coins flowing through financial pathways into two banking towers

I used to treat tithing and saving as two different kinds of money. Tithing belonged to the Sunday envelope. Saving belonged to the spreadsheet, where I could pretend future me was a very organized adult. Then I noticed something: both habits work better when I stop asking my mood for permission.

That is the behavioral-finance case for automating your tithe and your savings the same way. Not because generosity is a machine. Not because a bank transfer can make us holy. But because a clear intention is easier to keep when we give it a calendar, an amount, and a destination.

The future self is a charming procrastinator

Behavioral finance starts with a humbling observation: we do not always do what we said we would do, especially when the decision can be postponed. Automatic transfers are a small commitment device. The Consumer Financial Protection Bureau recommends automatic savings because moving a set amount on a regular schedule can help us save before the rest of the month spends the money for us.

There is a catch, and it is not a small one: automation should follow an honest look at income, bills, and cash flow. The CFPB warns that poorly timed transfers can lead to overdrafts. In other words, even good intentions need a decent calendar. Sanctity, meet spreadsheet.

One system, two directions

Imagine payday arrives. A pre-decided amount moves to savings. Another amount moves toward the church or charitable work you have chosen. The point is not to make the two destinations morally identical. They are not. The point is to give both values a place in the plan, before convenience and impulse start negotiating.

Research keeps finding that defaults and automatic features can reduce the friction of saving. A Vanguard study of 1.9 million 529 accounts describes automatic contributions as a behavioral commitment device and reports that many contributing accounts used them at least in part. The lesson is not “copy a percentage.” It is simpler: make the good choice easier to repeat.

For a tithe, that might mean an authorized recurring gift. For savings, it might mean a transfer to an emergency fund or retirement account. For either one, start with an amount that leaves room for rent, groceries, and the occasional tire that decides to become a theological crisis.

What to carry forward

What happened? A financial habit became a repeating system. What did it mean? My priorities stopped competing for whatever money happened to remain. What can I carry forward? Set the transfers, then review them monthly with a gentle examen: Did this plan fit reality? Did it express what I value? What needs adjusting?

Automation cannot replace attention. It can protect attention from having to renegotiate the same decision every payday. And sometimes formation is exactly that: fewer dramatic promises, more faithful little motions.

Life Insurance Isn’t an Investment First. It’s a Promise for the People Left Behind.

Glowing sphere enclosing a cottage, suitcase, keepsakes, and flowers

I used to think life insurance was mostly about guessing the future. How much will the mortgage be? What if college costs more than a small island? What if I live a long, healthy life and feel like I paid for nothing? The questions can turn a simple product into a fog machine.

Here is the plain version: life insurance is designed to move money to the people you name after you die. The National Association of Insurance Commissioners explains that every life policy has this basic purpose: pay a benefit to named beneficiaries. The policy is not mainly insuring your life in the way a warranty insures a washing machine. It is insuring the financial shock your absence might create.

That distinction matters. A paycheck can disappear. A mortgage does not perform a brief liturgy and forgive itself. Child care, debts, final expenses, and the ordinary costs of keeping a household upright can continue after one income stops. The NAIC Buyer’s Guide lists those needs as the sorts of hardships a death benefit may help address.

Term life is the cleanest example. You buy coverage for a set period, perhaps the years when children are young or a loan is large. If you die while the policy is in force, the beneficiaries receive the death benefit. If you outlive the term, the policy generally ends without a payout. That can feel strange until you remember what insurance is doing: transferring a risk, not promising a refund for staying alive. The California Department of Insurance describes term coverage in just those terms.

Permanent or cash-value insurance adds another layer. Whole life, universal life, and variable life can remain in force for life if their requirements are met, and they may build a cash value. That can be useful, but it also makes the contract harder to read. Cash value is not the same thing as the death benefit. Policy loans, surrender charges, changing assumptions, and missed premiums can affect what remains. The NAIC’s consumer guide notes that unpaid policy loans and interest can reduce what beneficiaries receive.

So what is life insurance actually insuring against? Not death itself. Death is stubbornly outside the product’s control. It is insuring against the financial dislocation that death can cause for someone else. That is why the first question is not, ‘Which policy has the most impressive illustration?’ It is, ‘Who depends on me, and what would still need paying if my income vanished?’

What happened: we turned mortality into a contract. What it meant: care can take a financial form without becoming less personal. What to carry forward: review the people named on the policy, the years of greatest need, and the promises your household would still have to keep. Then ask the unglamorous question that often does the most good: if I were gone, what would my family need—not forever, but next?

Bitcoin Mining Economics, Explained Simply: Revenue, Energy, and Risk

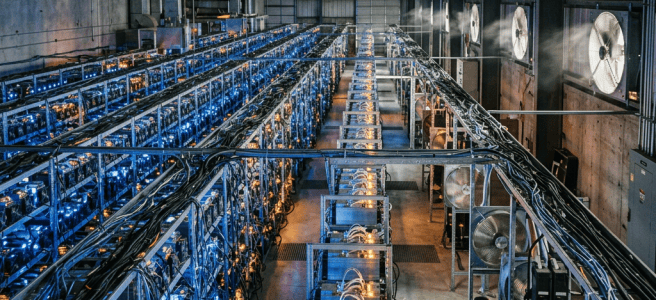
Rows of cryptocurrency mining machines with cables and cooling fans

I used to think Bitcoin mining involved tiny pickaxes and a very patient canary. The joke is bad, but the correction is useful: miners are not digging coins out of the internet. Specialized computers repeatedly hash block headers, trying to produce a result below the network’s target. The first valid result helps add a new block to Bitcoin’s transaction history. Bitcoin’s developer guide explains the mechanics without requiring a decoder ring.

So where does the money come from? A miner’s reward is two things: a block subsidy—newly created bitcoin—and the transaction fees attached to the transactions in that block. The protocol’s block-chain documentation calls these together the block reward. A solo miner keeps the whole payout, but may wait a long time between wins. A pool spreads the work among many miners and pays smaller, steadier amounts based on each miner’s share of the work. Think lottery ticket versus office pool, except the office has a warehouse full of humming machines.

The bill arrives every hour. Electricity is the obvious cost, but not the only one. There is specialized ASIC hardware, cooling, real estate, internet service, maintenance, financing, and the occasional experience of discovering that a hot computer room is not a spa. A miner is profitable only when the expected value of rewards covers those costs.

This is why energy price and machine efficiency matter so much. The Cambridge Centre for Alternative Finance’s methodology models profitability by comparing mining revenue with the electricity needed to run different generations of hardware. Its efficiency measure is joules per terahash: lower is better. Cambridge also notes that its electricity-price input is an assumption, not a universal fact, and that its model does not include every cost, such as maintenance and cooling. That is a helpful humility flag. A spreadsheet can be precise and still not know everything about the warehouse.

Competition adds another wrinkle. More miners do not make Bitcoin permanently easier to mine. The network adjusts difficulty every 2,016 blocks—aiming for about two weeks—so the target becomes harder or easier depending on how quickly blocks were found. The protocol documentation lays out that adjustment. More machines can mean more total computing power, but also a larger crowd reaching for the same scheduled reward.

And the reward itself is not fixed forever. The subsidy is cut at programmed intervals, roughly every four years, while transaction fees remain tied to demand for block space. That makes the business a moving target: price, fees, difficulty, electricity, machine prices, and the calendar all matter. The Congressional Research Service puts the broader point plainly: mining energy intensity tends to rise and fall with profitability, and when electricity and maintenance costs outrun revenue, operators may shut machines down or delay new purchases.

What happened? A digital currency turned security work into a competitive energy business. What did it mean? Mining is less like finding buried treasure and more like running a factory whose product, costs, and rules can all change. What can we carry forward? Whenever a crypto pitch says “the reward,” ask the quieter questions too: What are the costs? How often do they change? Who gets paid, and what happens when the easy money gets harder?

The Emergency Fund Is a Small Act of Faith

Stone mill and village homes surrounded by golden wheat fields

I used to think an emergency fund was what responsible adults had, like a label maker or strong opinions about lawn care. Then a car repair arrived with the confidence of a tax bill, and I remembered: preparation is not the same thing as fear.

An emergency fund is simply cash set aside for a problem you did not schedule. The Consumer Financial Protection Bureau names the usual suspects: car repairs, home repairs, medical bills, or a loss of income. It is not glamorous money. It is quiet money.

That quietness is the first spiritual clue. We often imagine faith as a dramatic leap. But much of ordinary faith looks more like keeping a lamp filled, a pantry reasonably stocked, or a promise made before the crisis arrives. An emergency fund says, without making a speech: tomorrow is worth caring for.

There is a reason the story of Joseph storing grain during seven abundant years has stayed in the cultural bloodstream. In Genesis 41, the plan is not hoarding for its own sake. The harvest is gathered so that a future famine will not ruin the country. Preparation becomes a form of service: a way to remain useful when circumstances turn hard.

That does not mean every household needs the same target. The common rule of thumb is three to six months of expenses for a serious income shock, while smaller spending shocks may call for a more modest first milestone. The FDIC also encourages starting with an amount you can build steadily, rather than waiting for a heroic surplus that never appears.

So the practical examen is gentle. What surprises tend to visit this household? Which bill would make the month wobble? What amount could move automatically on payday without turning the rest of the week into a small financial hostage situation?

Start with a number that is real. Maybe it is $25 a week. Maybe it is $500 over time. Keep it in a safe, accessible account, and give it a name that reminds you what it is for. When you use it, do not treat that as failure. The fund did its job. Rebuilding it is simply the next faithful repetition.

What happened? Life presented an unplanned bill. What did it mean? A little preparation bought room to respond without panic, shame, or expensive borrowing. What can we carry forward? Not a perfect balance, but a small habit of making tomorrow less fragile for the people entrusted to us—including our future selves.

Compounding Is Quiet Until It Isn’t

Young plant growing from a stack of coins on a garden path

I used to think compounding was a number that appeared in retirement articles wearing a necktie. Helpful, probably. But not exactly something you could feel.

Then I realized the point of compounding is that it feels like almost nothing for a surprisingly long time. It is the financial equivalent of putting leftovers in the fridge and discovering, three days later, that someone made soup. Quiet work. Useful result.

First, the plain-English version

Investor.gov defines compound interest as earning interest on interest. Start with $100 at 5 percent. After one year, you have $105. In year two, the 5 percent applies to $105, not merely the original $100, so you reach $110.25. That extra 25 cents is the whole idea in miniature: yesterday’s growth gets a chance to grow, too.

At first, the difference is pocket change. Later, it becomes the part you notice.

What 20 years looks like

Let’s use a deliberately boring example. Suppose you invest $100 at the end of every month for 20 years, and the account earns a hypothetical 6 percent annually, compounded monthly. You would contribute $24,000. Under that smooth assumption, the balance would be about $46,204. Roughly $22,204 of that total would be growth rather than money you deposited.

Those are not promised returns. They are a flashlight pointed at the mechanism. Real markets wobble. Fees and taxes matter. A constant 6 percent is a classroom ruler, not a weather forecast. The SEC’s Investor.gov calculator lets you change the initial investment, monthly contribution, time period, estimated rate, and compounding frequency so you can see how the assumptions alter the picture.

Vanguard offers another helpful mental image: in a hypothetical 6 percent example, $10,000 earns $600 in year one, but about $636 in year two because the return is now working on $10,600. By year 20, the annual gain is more than $1,800. Vanguard also stresses the fine print: returns vary, investing involves risk, and compounding works only when earnings remain invested.

The part nobody puts on a mug

Compounding does not feel like getting rich. It feels like repeating a small decision while the scoreboard remains unimpressed. Set up the transfer. Leave room for ordinary life. Resist the urge to demand a dramatic plot twist from every calendar year.

What happened? Small deposits and retained earnings shared the work. What did it mean? Time was not passive; it was an ingredient. What can we carry forward? Pick a contribution you can sustain, run the numbers with modest assumptions, and revisit the plan once in a while—not every time the financial-news kettle whistles.

Twenty years is a long time. It is also twenty years of ordinary months. That is where compounding lives.

The Catholic Case for Boring, Patient Investing

Tree on hill changing through winter, spring, summer, and autumn

I have a confession to make: I find “boring” reassuring. Give me a quiet Saturday, a pot of coffee, and an investment plan that does not require me to check my phone every twelve minutes. My younger self wanted a financial life with plot twists. My current self would like fewer plot twists, please.

That is one way into the Catholic case for patient investing. It is not a promise that markets will behave, or that every fund deserves a halo. It is a question of formation: What kind of person does my money practice me into becoming?

Patience is not passivity

Patient investing still makes choices. You decide what the money is for, how much risk you can bear, and what you are unwilling to support. The United States Conference of Catholic Bishops’ investment guidelines hold those pieces together: responsible financial stewardship, a reasonable return, prudence about risk, and attention to human dignity and the common good.

That is a sturdier picture than “maximize everything.” A return matters because resources support real obligations: a family, a parish, a future act of generosity. But the return is not the only question. The old Catholic word is stewardship, which means the money is entrusted to us, not enthroned over us.

Slow is a strategy

In practical terms, boring often looks like regular contributions, broad diversification, and a long time horizon. Investor.gov defines dollar-cost averaging as investing equal portions at regular intervals, regardless of market ups and downs. You buy more when prices are lower and less when they are higher. It is not magic. It is a way to keep one anxious afternoon from running the whole household.

FINRA explains that asset allocation and diversification can help manage investment risk by spreading money among and within asset classes. That does not make losses impossible; it does make the portfolio less dependent on one heroic bet. Even the phrase “heroic bet” sounds like something that ends with a lesson and a repair bill.

None of this means ignoring companies, communities, or conscience. A patient investor can read a fund’s holdings, ask how a manager votes, and decide which harms are incompatible with the family’s principles. Patience gives discernment time to work. Speculation often gives impatience a costume.

What is being formed?

What happened? I put money into a future I cannot see, then watched prices wiggle as if they knew I was watching. What did it mean? The account was never just a scoreboard; it was training my attention, my appetite, and my sense of enough. What can I carry forward? A simple rule: automate what serves the plan, review what deserves discernment, and refuse to confuse excitement with wisdom.

Perhaps the most countercultural investment move is not finding the next miracle. It is becoming the kind of person who can keep a promise across an ordinary Tuesday. What is your money asking you to practice: patience, prudence, generosity, or a little less phone-checking?